跳到主要內容

矽光子引爆光通訊漲停潮:磷化銦(InP)會是 AI 的下一個「稀土」嗎?

一句話結論: AI 算力之後,下一個瓶頸是「傳輸」——矽光子技術 1–2 年內將成主流,而其雷射光源核心材料磷化銦(InP)供應高度集中、擴產緩慢,這波光通訊漲停潮背後,是一場材料層的戰略卡位戰。
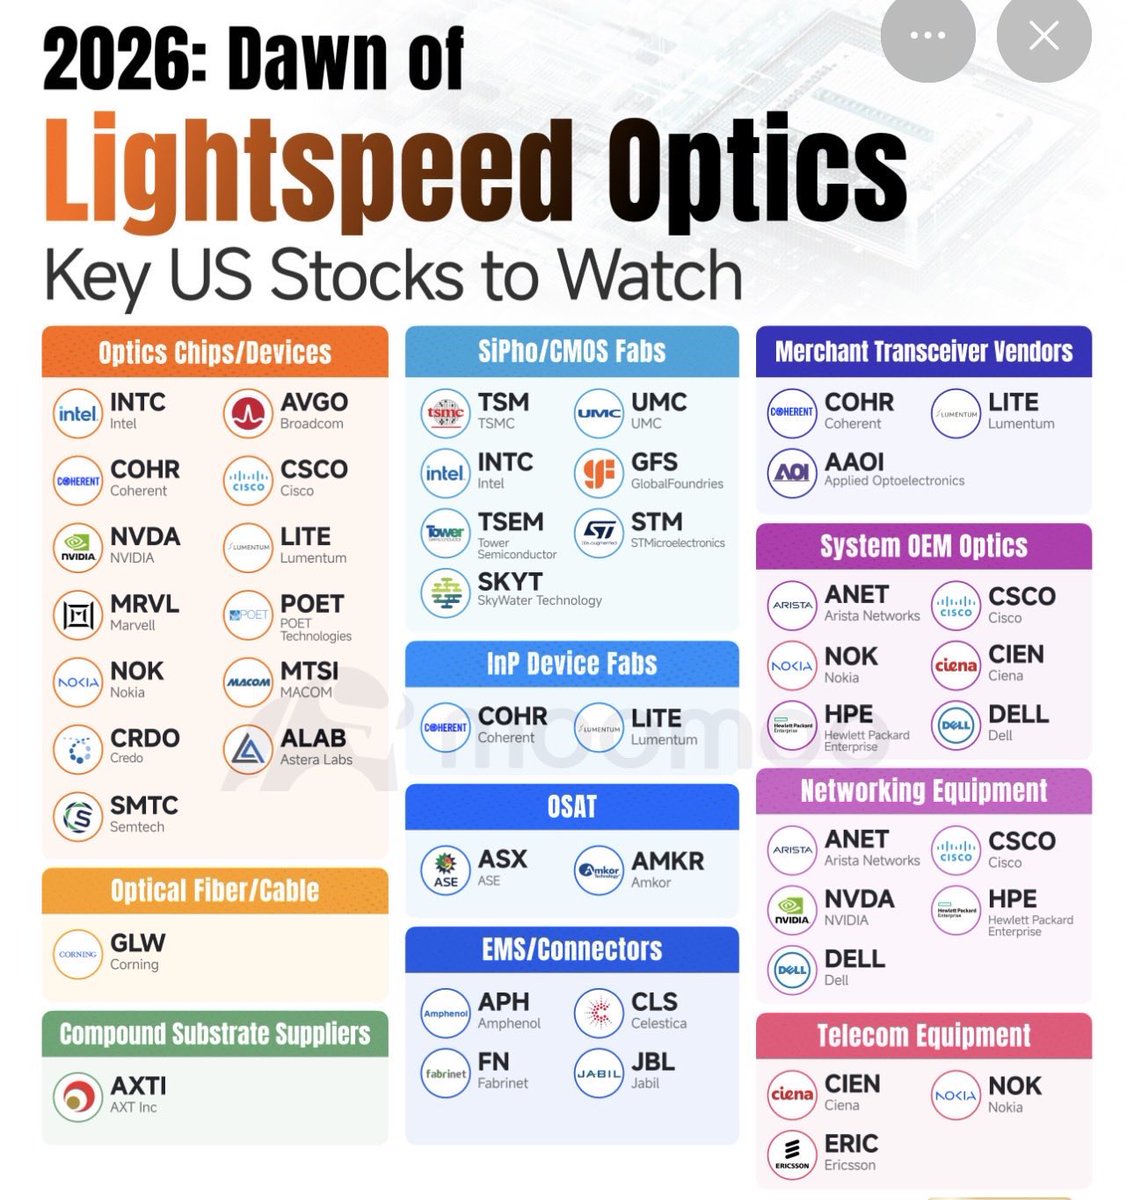
矽光子產業鏈全景:從光學晶片、代工到 InP 雷射工廠的十大分類

十檔漲停,「磷化銦」衝上熱搜

2026 年 8 月底,台股光通訊族群上演漲停潮,「磷化銦」一詞直接登上 Google 熱搜。催化劑有二:一是矽光子(Silicon Photonics)題材全面發酵;二是化合物半導體龍頭穩懋(WIN Semiconductors)公開表態——矽光子產品 1–2 年內可望成為市場主流,且「不擔心磷化銦缺料問題」。

一句話同時安撫了兩個市場情緒:需求是真的,供應也不怕。但磷化銦到底是什麼?為何值得整個產業嚴陣以待?

磷化銦:AI 資料中心的「點光者」

磷化銦(Indium Phosphide, InP)是 III-V 族化合物半導體,最大的本領是能高效地「發出光」與「接收光」。矽晶片擅長處理邏輯運算,卻很難直接發射雷射;而 AI 資料中心裡,GPU 之間的海量資料交換正從銅線轉向光纖——每一條光鏈路,都需要一枚由 InP 製造的雷射晶片。

這正是問題所在:矽光子負責調變與傳導光,但光源本身必須靠磷化銦。業界人士一針見血:「矽光子可以調製光,但它無法自己產生光源。」隨著 800G、1.6T 光模組放量、共同封裝光學(CPO)把光引擎推進交換器內部,對 InP 雷射的需求只會呈等比級數增長。

SK 海力士攜手研究機構在《自然電子學》發表的 CPO 路線圖:光子引擎與運算晶片的整合是大勢所趨

產業鏈卡位:誰在牌桌上?

從投研機構整理的產業地圖看,矽光子供應鏈大致分為四層:

  • 光學晶片設計:Broadcom、Coherent、Lumentum、Marvell、NVIDIA 等掌握核心元件;
  • 矽光子代工:台積電、聯電、Intel、GlobalFoundries 提供矽基光學晶圓製造;
  • InP 元件製造:Coherent 與 Lumentum 兩家寡頭主導雷射生產;
  • 上游材料:AXT、Sumitomo 等供應 InP 基板——最上游也最稀缺的一環。

穩懋的角色特別值得注意:它以砷化鎵(GaAs)射頻代工起家,全球市佔近六成,如今正把多年積累的化合物半導體量產能力延伸到光通訊領域。穩懋敢說「不擔心缺料」,底氣來自其對 III-V 族材料的深厚工程儲備——這也是市場願意買帳的原因。

先進半導體瓶頸地圖:穩懋在 InP 基板與雷射領域的角色日益關鍵

漲停潮之後:三個理性檢核點

一、缺料是真議題還是題材炒作? 先前 AXT 與 Lumentum 簽下長期供應協議、Coherent 直言「InP 產能是首要限制」,都證明瓶頸真實存在。但從擴產到量產通常需 2–3 年,短期股價反映的是預期而非獲利。 二、技術路線仍在演進。 薄膜鈮酸鋰(TFLN)、聚合物調製器等替代方案正在追趕,CPO 滲透速度也可能低於預期。今天漲停的公司,三年後未必都在牌桌上。 三、估值已搶跑。 光通訊指標股今年普遍大漲,本益比處於歷史高位。追高前不妨自問:如果 CPO 放量時程延後一年,這些公司撐得住現在的價格嗎?

常見問題 (FAQ)

Q1:磷化銦和矽有什麼不同?為何光通訊非它不可?

A:矽是間接能隙材料,無法高效發光;磷化銦是直接能隙材料,能高效產生雷射與偵測光訊號。每條光互連鏈路都需要光源,所以 InP 雷射無法被純矽方案取代。

Q2:矽光子是什麼?和現有晶片製程有何關係?

A:矽光子是在標準 CMOS 相容的矽晶圓上製作光學元件(波導、調變器、偵測器),可借用成熟半導體產線大量生產。它讓「光學」從昂貴的手工藝變成可規模化的晶片製造,是 AI 資料中心降本增效的關鍵路徑。

Q3:穩懋說不擔心缺料,可信嗎?

A:穩懋深耕化合物半導體(GaAs/InP)代工數十年,具備材料工程能力,且正積極擴充光通訊產能。但整條供應鏈的緩解仍取決於上游基板擴產,1–2 年內供需偏緊仍是大概率事件。

Q4:普通投資人如何參與這波趨勢?

A:除了直接持有相關個股,也可關注光通訊、半導體設備類 ETF。重點是區分「真有 InP/矽光子營收」的公司與純題材股,並留意估值水位與 CPO 導入進度。

Q5:如果 InP 缺料,替代方案有哪些?

A:短期內替代有限,因為光源物理特性難繞過;中長期可關注更高效的 VCSEL 方案、薄膜鈮酸鋰調製器搭配既有光源,以及各家的 6 吋 InP 晶圓轉換進度。

留言

這個網誌中的熱門文章

Intel 14A Defect Density Is Its Best Since 22nm — Is Intel Back in the Leading-Edge Race?

One-sentence takeaway: Intel's 14A process is cutting defect density faster than any node since 22nm, and customers have moved from watching to asking about capacity — if risk production stays on track for H2 2027, it's the strongest signal yet that Intel is back in the leading-edge game. "We have not seen this performance since 22nm." When Intel CFO David Zinsner dropped that line at the Deutsche Bank 2026 technology conference, the semiconductor world took notice. 14A — Intel's first 1.4nm-class node — is backing up the company's comeback story with data, not slogans. What is 14A, and why it matters 14A is Intel's most advanced planned process node, a "1.4nm-class" technology targeting high-volume manufacturing in 2028. It packs three headline technologies: second-generation RibbonFET gate-all-around transistors, PowerDirect backside power delivery, and High-NA EUV lithography. In short, it's the most technically complex node Intel ...

Google's Antitrust Remedies Enter Deep Water: Breakup, AI Mode, and the Browser

Bottom line: The U.S. DOJ's remedies phase against Google is redefining the commercial rules of "search" — from Chrome's fate to AI distribution and the ad business, every step could reshape global tech. Google's search monopoly case has been called "the most important antitrust case of the internet era." In August 2024, a federal judge ruled Google violated antitrust law; now the remedies phase is in deep water. The DOJ's proposals include breaking up the ad business, divesting Chrome, and ending default search agreements — each step ripples through the entire tech industry. Timeline: from monopoly ruling to remedies In August 2024, the D.C. federal court ruled that Google violated the Sherman Act by paying billions annually to make Apple, Samsung, and others set Google as the default search engine. The remedies trial runs through 2026, with DOJ options including: Breaking up the ad business: Google's ad tech stack is accused of stifl...

Why Is NVIDIA Spending Billions to Buy Up America's "Dark Fiber"?

One-line conclusion: NVIDIA is reportedly spending $5–10 billion to acquire long-haul "dark fiber" networks across the United States, signaling that the AI infrastructure race is shifting from raw compute power to the networks that connect it. NVIDIA is reportedly acquiring long-haul "dark fiber" networks across the United States, with total capacity estimated at 7.6 Pbps and a price tag between $5 billion and $10 billion. The news sent optical communications stocks surging globally: Taiwan's optical module makers jumped on July 22, and three more hit the daily limit on July 23. Many now read this as the moment the AI arms race moved from "who has more GPUs" to "who owns the network." What Is Dark Fiber, and Why Buy Instead of Lease? Dark fiber refers to fiber-optic cable that has already been laid but has no transmission equipment installed and carries no optical signal . The fiber cores sit "dark" and dormant, waiting to...